
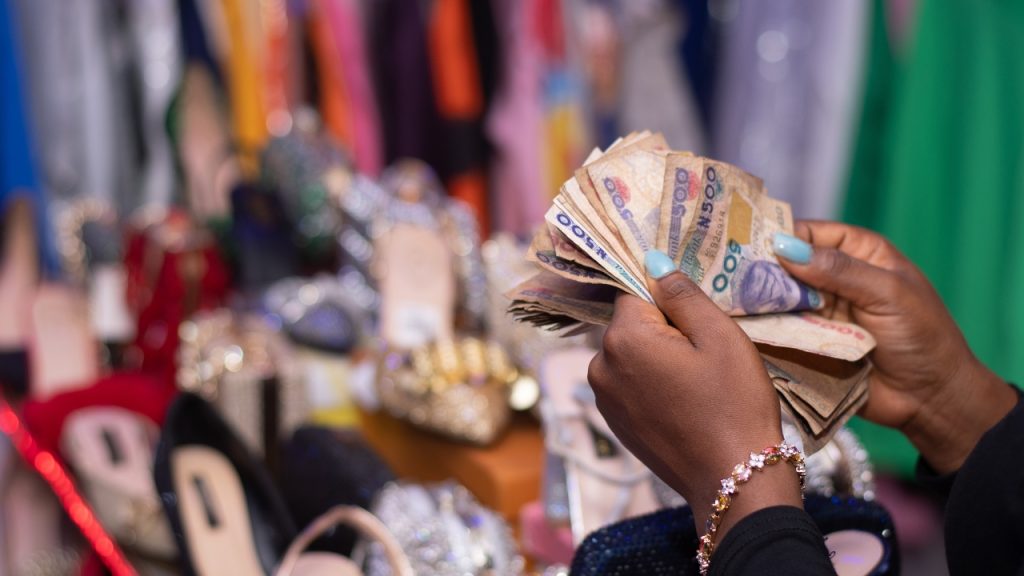
Every morning, before any bank opens its doors, a woman in a market in Kano is already banking with her Ajo contribution, handed to a trusted collector who will circle it back to her, plus everyone else’s, on a schedule the group agreed to months ago. No collateral. No credit score. No branch visit. Just trust, repeated often enough to become infrastructure.
This is informal finance, and for millions of African women entrepreneurs, it’s the primary financial system they operate in.
What “informal finance” actually looks like
Across the continent, this takes different shapes with the same core logic: Ajo and Esusu in Nigeria, Chama in Kenya, Stokvel in South Africa, tontines across Francophone Africa. Add to that informal moneylenders, supplier credit extended on trust between market traders, and family or community lending that never touches a bank ledger. None of it is regulated. All of it moves real money, at scale, every day.
Why women lean on it — and it isn’t about literacy
The easy story is that women use informal finance because they lack financial literacy. That story doesn’t hold up in the field. Women running SME businesses in places like Kano and Ilorin are often financially sophisticated, they track margins, manage supplier relationships, and price risk daily. What they lack is access: collateral requirements that assume land or property ownership skewed toward men, documentation demands that formal lenders won’t waive, and, in many Muslim-majority communities, a financing gap where interest-based lending conflicts with Islamic finance principles and few Sharia-compliant alternatives exist locally.
Financial literacy training addresses none of that. You can teach a woman to build a cash flow projection, and she still won’t qualify for a loan if the underlying eligibility criteria were never built with her in mind. The barrier is structural, not educational.
The double edge
Informal finance deserves real credit, not just as a stopgap. It’s flexible, community-governed, and built on trust that formal underwriting can’t replicate. But it has a ceiling. Group savings pools are only as large as the group’s combined savings — they can smooth cash flow, but rarely fund the kind of growth capital a scaling business needs. Informal moneylenders can be predatory. And because none of it is recorded in a way formal institutions recognize, a woman can have a flawless repayment history for a decade and still show up as “no credit history” to a bank.
Organisations building the bridge — and how to actually get in
The good news: informal finance is increasingly being connected to formal systems, deliberately, by organizations that understand both worlds. None of these require a loan application in the traditional sense — access usually runs through a local facilitator, cooperative, or implementing partner already active in a community, not a branch or a portal.
CARE International runs the most widely replicated model, the Village Savings and Loan Association (VSLA). Groups of 15 to 25 people meet regularly to pool savings, access small loans, and build emergency insurance, with the model supporting more than 8 million members since 1991, most of them women. Its LINK Up initiative goes a step further — connecting 10,000 VSLAs directly to formal financial institutions in Kenya and Tanzania, turning an informal savings record into something a bank will recognize. Access: through CARE’s country offices, or the local NGOs and cooperatives that implement CARE-aligned savings programmes in a given community.
Oxfam runs its own version under different names depending on the country, VSLAs in Nigeria, Saving for Change in Mali. In Nigeria, Oxfam’s VSLAs are self-managed community groups of 15 to 25 people who meet weekly or fortnightly to save and borrow, with savings and earnings shared out after roughly a year, and the model is active specifically in states like Kebbi and Adamawa as part of rural resilience programming. Access: through Oxfam Nigeria’s field offices or the local partner organizations delivering its rural livelihoods and resilience projects.
Plan International takes a similar approach with a younger-skewing focus. It supports savings groups across 28 countries so that people, especially young women, can confidently access financial services and build saving and investment skills. Access: through Plan International’s country programmes, usually bundled with youth economic empowerment or girls’ education initiatives already running in a community.
BRAC stands out for building a formal pathway on top of the informal one. Its model starts women in community savings groups, then moves them into BRAC’s own microfinance institutions once they’re ready to scale. In its AIM programme, more than 13,000 young women set up 630 savings groups, collectively saving over $230,000, with some going on to become clients of BRAC’s microfinance branches. BRAC’s group-based loans are collateral-free and designed specifically for women micro-entrepreneurs who lack formal credit history, effectively formalizing the trust-based lending an Ajo group already runs on. Access: through BRAC’s country offices in Uganda, Tanzania, Sierra Leone, Liberia, Rwanda, and Ghana, where its savings-group and microfinance branches operate directly in communities.
This is where SLA’s role becomes clear. Digital skills, the kind SLA builds through BoostHer, aren’t a replacement for informal finance, and they’re not positioned as one. They’re the bridge: the ability to digitize records, build a visible transaction history, and present a business in a way that formal capital providers and platforms like ConnectHer can actually evaluate. A woman doesn’t have to choose between her Ajo group and a bank loan. With the right digital tools, her Ajo history becomes evidence a bank can use.
The reframe
Informal finance isn’t a phase women “graduate out of” on the way to real banking. It’s real banking — proven, trusted, and running at a scale formal institutions still can’t reach in the same communities. The work isn’t to replace it. It’s to build the connective tissue — through organizations like CARE, and through digital skills that make informal financial histories legible to formal systems — so that women don’t have to leave one system behind to access the other.
-
Before You Plan 2027, Look Back
Usually, this is the part of the year where everyone starts shouting: new year, new you, new goals, new everything. The lists get longer, the pressure gets louder, and somewhere in the rush, we forget to say thank you to the woman who got us here. So before all of that, we just want to…
-
Hair Experts Explain Why Most Relaxer Damage Happens
Why is your relaxed hair breaking? These are the 5 causes of relaxer damage, ranked, plus how to tell over-processed hair from dry hair.
-
How Busy Nigerian Women Keep Their Homes Mosquito-Free
A mosquito routine that fits a working week: ten minutes each evening, five on Saturday, and a few seasonal jobs, with a plan for when the power goes.
-
How to Protect Your Home From Bed Bugs and Hidden Pests
Bed bugs need searching, heat and encasements, not just a spray. How to spot them, treat them properly, and keep cockroaches and ants out of your home.
-
Is Relaxer Bad for Your Hair? The Truth, Explained
Relaxer myths debunked by the chemistry, not opinion. Learn what relaxer really costs your hair, why results differ, and how to keep relaxed hair healthy.
-
Grants and Funding for African Women Entrepreneurs: How to Prepare for 2027
The year is rounding up. Between end-of-year deadlines, holiday orders and “I’ll think about it in January,” it is tempting to pause your big plans until the new year starts. Here is what is happening on the other side of the table: funders, accelerators, development partners and corporates are already planning next year. Budgets are…